
Yield to maturity (or yield to worst for credit instruments trading above par) is often the number that gets quoted first when the perspective return of a credit is discussed. A yield is a total annualized return measure, one that counts coupon income and any capital gain or loss to the given redemption date, relative to the price paid. For a performing credit bought at or near par and held to redemption, that return is close to fixed. The payoff looks a lot like selling a put on the value of the business: your upside is largely capped at the annualized interest and capital gain, while your downside is the entire principal. That asymmetry is why credit analysts spend so much of their time on the left tail (the downside).
But the fixed-return picture is a simplification. Investors in performing public credit can earn more than the stated yield by taking advantage of price appreciation through an interim holding period. This can be achieved via roll-down along the upward sloping shape of the yield curve as time passes or through an event that re-rates the spread on the credit. Of course, under both set ups, the analyst still has to use fundamental analysis to protect the downside – but upside returns through the interim holding period can be more attractive than the stated yield.
What is an interim holding period return?
An interim holding period return is the return you expect to earn between purchase and a planned exit before the maturity or worst date, made up of coupon income plus any change in the bond's price. Buying and holding a performing credit to redemption or maturity pretty much fixes the realized return on an annual basis, apart from floating-rate loans, but there are ways to boost the return over an interim holding period.
FE's Guide to Success for New Buyside Credit Analysts frames the resulting shift in the question. It moves from what a bond yields to what return you can earn over your expected holding period, what has to happen to earn it, and what assumptions sit inside that target.
How does roll-down add to a bond's return?
Roll-down adds to a bond's return when its yield falls as it ages along an upward-sloping yield curve, so you collect the coupon and also sell at a higher price than you paid. The return splits into a carry return from the coupon and a roll-down return from capital appreciation.
The Your First 6 Months on the Credit Desk webinar illustrates it with an unsecured bond that has a 6% coupon and eight years to maturity, priced at 90 as of September 30, 2026. Held to maturity, it earns roughly a 7.7% yield to maturity. In the example, the bond’s modified duration is 6.1 years today and would be 5.6 years in a year, and a pari passu bond in the same capital structure with a 5.6 year duration yields 7.32%. If the subject bond's yield falls to that level a year from now, its price would be roughly 93, which produces a one-year holding period return of about 10% against the 7.7% yield to maturity at purchase.
How do spread tightening and event-driven trades lift returns further?
Spread tightening lifts returns by adding price appreciation when spreads normalize or an issuer's credit improves, and event-driven trades are built around a specific catalyst the analyst expects to cause that re-rating. The example in the webinar shows what happens when we add a spread tightening component to the worked example. If your thesis is that the issuer will sell assets and use the proceeds to deleverage, and spreads tighten by 75 basis points to a 210 basis point target (implying a 6.55% yield to maturity on a one year forward basis), the one-year exit price becomes 97 and the holding period return rises to almost 15%.
For credit-focused hedge funds and opportunistic credit funds, a credit with a six or seven percent yield to maturity only becomes an opportunity that meets a target return profile in the low to mid teens if there is an event-driven spread tightening.
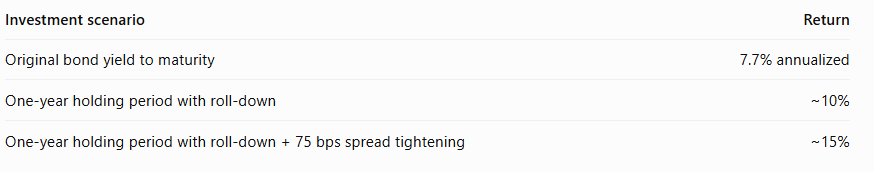
Here's how roll-down and spread tightening affect the potential return of the same bond over a one-year holding period.
From the webinar replay:
"Event-driven credit is one of these buzzwords that's thrown around by a lot of people when they're talking about opportunistic credit funds or credit hedge funds. It's important to understand why that is. And in a performing credit context, this kind of event-driven return profile is what's necessary to bring the return of performing credit up to the hurdle rates that these opportunistic credit funds often have."
A catalyst also has to be material: the event usually has to change the leverage outlook enough to move the credit into a different comps group to catalyze a rerating.
An extreme spread-tightening example is a Boeing 30-year new issue from May 2020, still during the early stages of the pandemic. The bond was issued at par at a 456 basis point spread, had a very long duration, and was callable only six months before maturity (effectively not callable). The price appreciated to 136 by year end, and including coupon income the trade returned about 40% over seven months. It differs from an event-driven trade because there was no hard catalyst, but the thesis was that spreads would normalize.
How do you test the downside to a holding period return?
You test it with a break-even analysis, which sets the upside case against how far yields or spreads must move against you before your return over the holding period reaches zero. The webinar applies this to a 5.8% coupon bond trading at par two years prior to maturity. It would need to trade at about 94 and a quarter, a 12.1% yield at the forward date, before a one-year holding period return turns negative. That is more than double the bond's current yield, which would be very unlikely unless the underwriting was completely wrong.
This type of check matters to frame what would need to happen to lose money on a trade. From Credit Academy's lesson on roll-down trades:
"I would constantly be running these types of analyses, to say, let's suppose I get this wrong, and there's some sort of adverse movement in the shape of the curve or a parallel move in the curve, what is my break-even for where I at least won't lose money on this trade? And so running these types of numbers let me become comfortable with a lot of these types of investment theses."
If you find this interesting, join us in our Credit Academy, where we cover relative value analysis, returns composition, and public credit thesis types in Module 4 for investors who want to work through the full process.
Credit Academy instructor
Alex Goston, Instructor
Alex has over a decade of credit investing experience across distressed, opportunistic, and performing credit. With experience on both the public and private side of credit investing at KKR and RBC Global Asset Management, Alex brings expertise in deep fundamental credit analysis.